
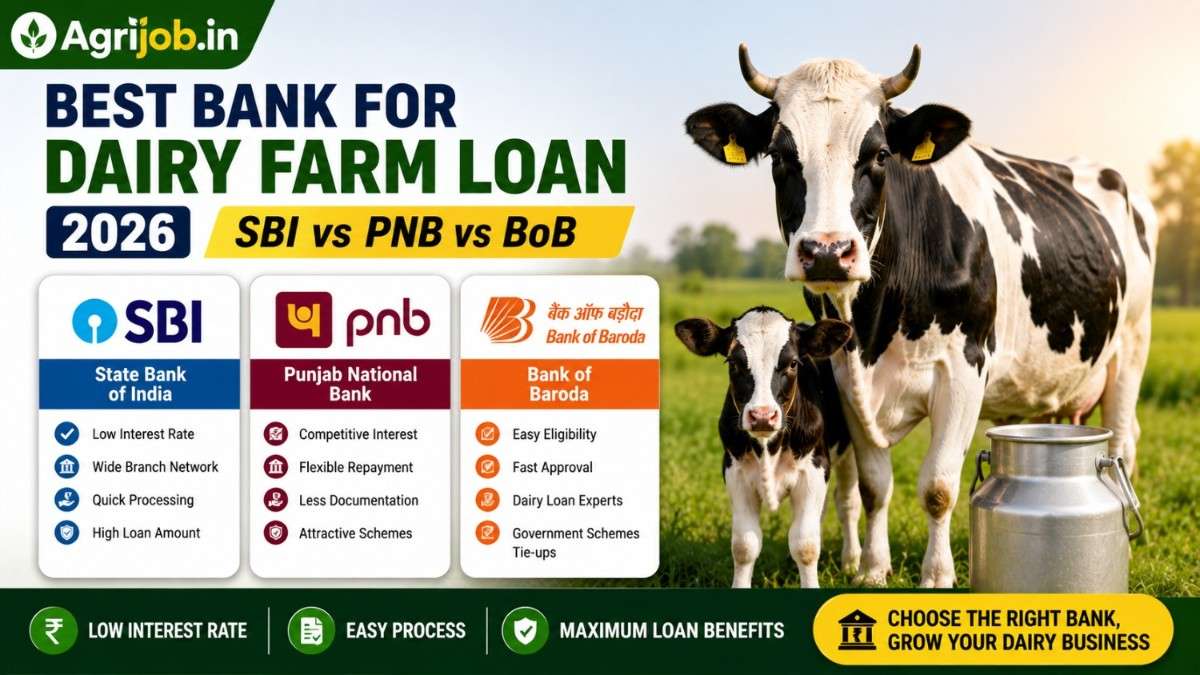
Best Bank for Dairy Farm Loan 2026: SBI vs PNB vs BoB
Best bank for dairy farm loan 2026 — SBI starts at 7.50% p.a., Bank of Baroda at 8.70%, and Central Bank’s Cent Dairy Scheme at 8.75%. But the interest rate alone doesn’t determine which bank is right for you. The scheme you qualify for, the collateral threshold, the processing speed at your nearest branch, and whether your project is eligible for the Government’s 3% AHIDF interest subvention matter far more. This guide covers all 6 major public sector banks, updated with October 2026 MCLR benchmarks and the latest AHIDF data, so you can compare and choose confidently. This is for Indian farmers, dairy entrepreneurs, SHG members, and rural youth aged 20–55 planning a 2-animal mini unit or a 100-cow commercial dairy setup.
For a 2–10 animal mini dairy unit, Bank of Baroda (8.70% p.a., zero processing fee up to Rs.3 lakh) and Union Bank (up to 84 months repayment, collateral-free up to Rs.2 lakh) offer the most clearly structured dairy loan terms. For society-linked or AHIDF-backed large projects, SBI (from 7.50% p.a.) is strongest. All banks qualify for NABARD DEDS subsidy of 25%–33.33%.
- Banks Covered: SBI, Bank of Baroda, PNB, Union Bank, Canara Bank, Central Bank of India
- SBI Rate (Oct 2026): 7.50% p.a. onwards (allied activities); 1-Yr MCLR = 8.80%
- Bank of Baroda Mini Dairy Rate: 8.70% p.a. (MCLR-linked); zero processing fee up to Rs.3 lakh
- Cent Dairy Scheme Rate: 8.75% p.a.; 0.30% processing fee above Rs.3 lakh
- Collateral-Free Limit: Rs.1.6 lakh (BoB) | Rs.2 lakh (Union Bank, Canara Bank)
- Repayment Period: 5–7 years; moratorium of 3–6 months for animal productivity
- AHIDF Subvention: 3% per annum for up to 8 years (DAHD pays directly to bank)
- DEDS Subsidy: 25% general / 33.33% SC/ST back-ended capital subsidy via NABARD
- DIDF Rate for Cooperatives: 6.5% p.a. (loans via NDDB/NCDC to dairy societies)
- AHIDF Projects Approved (July 2026): 439+ projects worth Rs.21,190 crore
- 1. Dairy Farm Loan Interest Rates 2026 – What Banks Actually Charge
- 2. SBI Dairy Loan Schemes 2026
- 3. Bank of Baroda Dairy Loan Scheme 2026
- 4. PNB Dairy Loan Scheme 2026
- 5. Union Bank Dairy Sector Financing 2026
- 6. Canara Bank Dairy Loans 2026
- 7. Central Bank of India Cent Dairy Scheme 2026
- 8. Regional Rural Banks and Cooperative Banks
- 9. AHIDF and NABARD DEDS – Government Subsidy Routes
- 10. Bank vs Bank Comparison Table 2026
- 11. Who Should Apply – 8 Applicant Profiles
- 12. How to Choose the Right Bank for Your State
- 13. Common Documents Required
- 14. Pros and Cons of Public Bank Dairy Loans
- 15. Important Dairy Loan Terms You Must Know
- 16. Important Links
- 17. Conclusion
- 18. Key Takeaways
- 19. Frequently Asked Questions
Dairy Farm Loan Interest Rates 2026 – What Banks Actually Charge
Dairy farm loan interest rates in 2026 are benchmarked to MCLR (Marginal Cost of Funds Based Lending Rate) or EBLR (External Benchmark Lending Rate). As of October 2026, SBI’s 1-year MCLR stands at 8.80% and Union Bank’s at 8.80% (effective July 21, 2026), with the RBI repo rate at 8.00% for most EBLR-linked products. The actual rate you pay is this benchmark plus a bank-specific spread. For dairy and allied activities, SBI currently charges from 7.50% p.a. onwards — indicating a negative spread or subvention for priority-sector dairy lending. Here are the verified 2026 rates:
| Bank | Scheme Name | Rate (2026) | Processing Fee | Max Amount |
|---|---|---|---|---|
| SBI | Allied Activities – Dairy | 7.50% p.a. onwards (w.e.f. 15.10.2026) | Confirm with branch | Rs.5 lakh (Dairy Plus) / Rs.50 cr (Agri Enterprise) |
| Bank of Baroda | Scheme for Financing Mini Dairy Units | 8.70% p.a. (MCLR-linked) | 0% up to Rs.3L; 1% above | Rs.6 lakh (2–10 animals) |
| PNB | Dairy Development Programmes / KCC | MCLR-linked; confirm branch | Confirm with branch | As per project |
| Union Bank | Finance to Dairy Sector | MCLR+spread; 8.80% base (Jul 2026) | Confirm with branch | As per project |
| Canara Bank | Dairy Loans | MCLR-linked; 2.30% spread on agri loans above Rs.3L | Confirm with branch | As per project |
| Central Bank of India | Cent Dairy Scheme | 8.75% p.a. onwards | 0% up to Rs.3L; 0.30% above | As per project profitability |
| AHIDF (any bank) | Animal Husbandry Infrastructure Fund | Bank rate minus 3% GoI subvention | As per lending bank | Rs.1 lakh – Rs.100 crore |
| DIDF (Cooperative route) | Dairy Infrastructure Development Fund | 6.5% p.a. (via NDDB/NCDC) | NA – NABARD funded | Society/cooperative projects |
SBI Dairy Loan Schemes 2026
SBI (State Bank of India) is India’s largest public sector bank with over 22,000 branches and dedicated agri-rural banking verticals in every district. Its dairy lending falls under Allied Activities — Dairy, Poultry & Fisheries, with rates from 7.50% p.a. effective October 15, 2026. Two key schemes apply:
- 🥛 SBI Scheme for Dairy Societies: For registered “A” Grade Milk Societies — finances milk house/society office, automatic milk collection systems, transport vehicles, and bulk chilling units. Minimum supply: 1,000 litres/day to the milk union. Requires a clean 2-year audit record. Best for AMUL-pattern or district-level milk union-affiliated societies.
- 🐄 SBI Dairy Plus Agriculture Loan Scheme: For individual milk-producing members of AMUL Pattern Societies — covers dairy shed construction, milking animals, milking machines, and chaff cutters. Maximum term loan: Rs.5 lakh. Margin: nil up to Rs.50,000; 10% for Rs.50,000–Rs.5 lakh.
- 💳 SBI Kisan Credit Card (KCC): Working capital for dairy animals at 7% p.a. (GoI interest subvention applies) up to Rs.3 lakh; above Rs.3 lakh at MCLR-linked rates. A cost-effective route for recurring dairy working capital needs.
- 🏗️ SBI AHIDF Route: For MSMEs and private entrepreneurs, SBI participates in the AHIDF scheme — EBLR + 200 bps with 3% GoI interest subvention. Loan up to Rs.100 crore with a 2-year moratorium and 10-year repayment.
Bank of Baroda Dairy Loan Scheme 2026
Bank of Baroda’s primary dairy product is the Scheme for Financing Mini Dairy Units at 8.70% p.a. — one of the few banks that publishes a named dairy rate rather than a pure MCLR reference. This makes planning your EMI and project cost easier before you visit the branch.
- 🐃 Unit size: 2 to 10 milch animals (cows/buffaloes). Per-animal cost as per NABARD’s regional office rate for the concerned state.
- 💰 Loan amount: Minimum Rs.60,000 (2 animals); maximum Rs.6 lakh (10 animals). Repayment: 5 years with 3-month moratorium.
- 👥 Eligible applicants: Individuals, farmers, NGO members, SHG members, JLG members.
- 🔒 Collateral: Not required below Rs.1.6 lakh. Above that: equitable/registered mortgage or third-party guarantee.
- 💸 Processing fee: Zero up to Rs.3 lakh; 1% above Rs.3 lakh — one of the lowest in the sector.
- 💳 Baroda AH & Fisheries KCC: Separate working capital line for Rs.3,000–Rs.10 lakh range to cover feed, veterinary, and routine dairy expenses.
PNB Dairy Loan Scheme 2026
Punjab National Bank runs a Scheme for Financing Dairy Development Programmes under its broader agriculture credit umbrella. PNB does not publish a single consumer-facing fixed dairy rate, so applicants must check with their branch for the current MCLR-linked rate. PNB is particularly strong for:
- 📋 Kisan Credit Card (KCC): Available for dairy animal working capital. GoI interest subvention at 2% p.a. applies on KCC loans up to Rs.3 lakh, bringing effective rate to 5% for timely repayers.
- 🏘️ Krishi Bhu Swami Yojana: For land-backed agricultural credit including dairy infrastructure — useful for farmers who have land to offer as collateral and want a larger term loan.
- 🏦 PMRY/MUDRA route: PNB participates in Pradhan Mantri MUDRA Yojana — Tarun loans up to Rs.10 lakh can be used for dairy animal purchase without land collateral.
- ⚠️ Key point: PNB’s branch-level dairy lending is strong in Punjab, Haryana, and UP — key milk-belt states — where local branch staff are most familiar with dairy project appraisal.
Union Bank Dairy Sector Financing 2026
Union Bank of India’s Finance to Dairy Sector scheme stands out for its longest repayment tenure of up to 84 months (7 years) — giving dairy farmers the most breathing room to build revenue before their full EMI kicks in. Union Bank’s 1-year MCLR was 8.80% effective July 21, 2026, with EBLR (repo-linked) at 8.00%.
- 🔒 Collateral up to Rs.2 lakh: Hypothecation of assets created from bank finance only — no land or third-party guarantee needed.
- 🏦 Collateral above Rs.2 lakh: Hypothecation plus mortgage of land (minimum land value = loan amount) and/or third-party guarantee.
- 📅 Repayment: Up to 84 months — the most generous tenure among the six banks compared.
- 🐄 Coverage: Mini dairy units and commercial dairy units — one scheme covers both scales.
- 💳 Prepayment: Allowed; prepayment penalty may apply as per the loan agreement terms.
Canara Bank Dairy Loans 2026
Canara Bank’s Dairy Loans scheme has India’s most operationally detailed eligibility criteria — which signals the bank is genuinely equipped to evaluate dairy projects rather than treating them as generic agri loans. Canara’s agricultural interest rate structure (from its August 18, 2026 ROI circular) shows a base MCLR spread of 2.30% for agri loans above Rs.3 lakh up to Rs.1 crore.
- 🏠 Shed requirement: Farmer must have adequate cattle shed for existing and proposed animals before loan sanction.
- 🌱 Fodder requirement: Must be cultivating green fodder or have a verified supply arrangement.
- 💧 Water and vet access: Drinking water source and veterinary/AI (artificial insemination) services must be readily available in the area.
- 🐄 Animal quality: Only heifers/animals of good breed and good health eligible; non-descript animals not financed.
- 📈 Milk marketing assurance: Assured marketing route for milk produced must be documented — cooperative tie-up, AMUL, or private dairy company letter.
- 🔒 Collateral: Nil margin and nil collateral up to Rs.2 lakh (hypothecation of assets only); 15–25% margin above Rs.2 lakh.
- 👥 Eligible applicants: Farmers, individual entrepreneurs, NGOs, companies, SHGs, dairy cooperative societies, milk unions, milk federations.
Central Bank of India Cent Dairy Scheme 2026
Central Bank of India’s Cent Dairy Scheme is one of only two banks (with BoB) that publish a specific dairy loan interest rate: 8.75% p.a. with a processing fee structure of 0% up to Rs.3 lakh and 0.30% above Rs.3 lakh. This makes it the most straightforward to cost-compare at the planning stage.
- 💰 Rate: 8.75% p.a. — slightly higher than BoB’s 8.70% but with lower processing fee above Rs.3 lakh (0.30% vs 1%).
- 👥 Eligible applicants: Farmers, individuals, groups of farmers, companies, societies, firms, and NGOs.
- 📄 Loan amount: Based on project profitability and borrower’s repayment capacity — no publicly stated ceiling for commercial units.
- 🏦 Repayment: Tenure based on project cash flows; confirm current moratorium norms with branch.
- ⚡ Author’s note (Nitish Singh): As a former Central Bank of India loan officer, the Cent Dairy Scheme’s flat processing fee structure and borrower-inclusive eligibility (firms, companies, NGOs) make it genuinely one of the most inclusive dairy financing options for non-farmer entrepreneurs.
Regional Rural Banks and Cooperative Banks for Dairy Loans
Regional Rural Banks (RRBs) and State Cooperative Banks are NABARD-eligible refinancing institutions for all dairy schemes — often overlooked but highly effective for small and marginal farmers in remote areas. For a farmer in a village 40 km from the nearest commercial bank branch, a local Grameena Vikas Bank or State Cooperative Bank is often the fastest route to dairy financing.
- 🏘️ Local land familiarity: RRB staff know the patwari system, local khasra-khatauni records, and cooperative milk society linkages in your block — reducing back-and-forth document verification that delays commercial bank loans.
- 👥 Cooperative milk union tie-ups: Many state cooperative banks work directly with district milk unions (e.g., Bihar State Milk Co-operative Federation / COMFED) for streamlined project report verification.
- 📍 Examples of active RRBs: J&K Grameen Bank, Baroda UP Bank, Baroda Rajasthan Kshetriya Gramin Bank, Madhyanchal Gramin Bank — all run NABARD-refinanced dairy loan products at competitive rates.
- 💰 Bihar example: Bihar government approved Rs.316 crore for dairy infrastructure via COMFED under SIDBI support in 2025–26 — channelled partly through cooperative and regional banks at state-subsidised rates.
AHIDF and NABARD DEDS – Government Subsidy Routes 2026
Two major government subsidy routes can be combined with any bank loan from the above list to dramatically reduce your effective interest cost or principal outflow:
| Scheme | Subsidy / Benefit | Who Qualifies | Administered By |
|---|---|---|---|
| DEDS (Dairy Entrepreneurship Development Scheme) | 25% back-ended capital subsidy (general); 33.33% (SC/ST/women) | Individuals, SHGs, cooperatives, dairy units with 2–10 animals minimum | NABARD via scheduled banks |
| AHIDF (Animal Husbandry Infrastructure Development Fund) | 3% p.a. interest subvention for up to 8 years (including 2-yr moratorium) | MSMEs, FPOs, cooperatives, private companies — dairy processing, value-added products, infrastructure | DAHD (Dept of AH & Dairying); via participating banks |
| DIDF (Dairy Infrastructure Development Fund) | Loan at 6.5% p.a. (DAHD subvention to NABARD, passed to NDDB/NCDC) | Milk cooperatives and dairy societies only — for processing and chilling infrastructure | NABARD to NDDB/NCDC to milk unions |
| Interest Subvention Scheme (ISS) | 2% p.a. interest subvention on short-term agri/allied-activity loans | All farmers with KCC/short-term crop or dairy loans up to Rs.3 lakh | GoI via banks; 3% additional for prompt repayment (effective rate 4%) |
A 10-animal dairy unit costing Rs.5 lakh qualifies for Rs.1.25 lakh DEDS subsidy (general) or Rs.1.67 lakh (SC/ST). You take an Rs.5 lakh bank loan, repay normally, and after 3–6 months of regular repayment, NABARD releases the subsidy back-ended to your loan account — reducing outstanding principal. On a Rs.5 lakh BoB loan at 8.70% for 5 years, this saves approximately Rs.25,000–Rs.35,000 in interest. Always apply for DEDS through your bank before or simultaneously with the loan — not after disbursal.
Best Bank for Dairy Farm Loan 2026 – Comprehensive Comparison
| Factor | SBI | Bank of Baroda | Union Bank | Canara Bank | Central Bank | PNB |
|---|---|---|---|---|---|---|
| Named Dairy Scheme | Dairy Plus / Dairy Societies | Mini Dairy Units Scheme | Finance to Dairy Sector | Dairy Loans | Cent Dairy Scheme | Dairy Dev. Programmes |
| Published Dairy Rate (2026) | 7.50% p.a. onwards | 8.70% p.a. | MCLR-linked (8.80% base) | MCLR+2.30% spread | 8.75% p.a. | MCLR-linked |
| Collateral-Free Up To | Rs.50,000 (no margin) | Rs.1.6 lakh | Rs.2 lakh | Rs.2 lakh | Confirm branch | Confirm branch |
| Max Repayment Tenure | 5 years | 5 years + 3-month moratorium | 84 months (7 years) | As per project | As per project | As per project |
| Processing Fee | Confirm branch | 0% up to Rs.3L; 1% above | Confirm branch | Confirm branch | 0% up to Rs.3L; 0.30% above | Confirm branch |
| AHIDF Participation | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes |
| DEDS Subsidy Eligible | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes |
| Best For | Society-linked; large AHIDF projects | 2–10 animal mini dairy units | Commercial dairy; long EMI needed | Farmers with assured milk marketing | Inclusive eligibility; firms/NGOs | Milk-belt states: Punjab, Haryana, UP |
For 2–10 animal mini units: Bank of Baroda (8.70%, zero fee up to Rs.3L, clear collateral rules) is the easiest to plan around.
For longest repayment flexibility: Union Bank (84 months, Rs.2 lakh collateral-free) gives maximum breathing room for new dairy units still building revenue.
For the lowest rate overall: SBI (7.50% p.a. allied activities) — but confirm your unit qualifies as an allied activity at your specific branch.
For companies, NGOs, and firms: Central Bank’s Cent Dairy Scheme (8.75%) accepts the broadest entity types.
For AHIDF large infrastructure: Any of the six banks qualifies — choose the one with the best agri branch in your district.
Universal rule: Prioritise the bank with the strongest dairy-lending relationship in your district over a 0.25% rate difference — faster processing saves more money than marginal rate savings.
Who Should Apply for a Dairy Farm Loan in 2026?
- 🧑🌾 Individual small farmers (2–10 animals): Apply under BoB’s Mini Dairy scheme or Canara Bank Dairy Loans — both have clear criteria and NABARD DEDS subsidy eligibility.
- 🥛 AMUL Pattern / Milk Society members: SBI Dairy Societies Scheme is purpose-built for you — faster approval due to existing society audit records.
- 👥 SHG and JLG members: BoB Mini Dairy, Union Bank Finance to Dairy Sector, and PMEGP via any bank are the best routes — group-based lending reduces collateral requirement.
- 🏭 Dairy entrepreneurs (processing, chilling, packaging): AHIDF via SBI/BoB/Union Bank — up to Rs.100 crore loan with 3% GoI subvention for 8 years.
- 👩🌾 SC/ST and women farmers: DEDS subsidy increases to 33.33% — effectively Rs.1.67 lakh back on a Rs.5 lakh unit. Any bank can process this.
- 🏘️ Farmers in milk-belt districts (UP, Bihar, Rajasthan, Punjab, Gujarat): Your district lead bank is likely already active in dairy lending — start there.
- 🏢 Companies, firms, NGOs, dairy cooperatives: Cent Dairy Scheme (Central Bank) or AHIDF via SBI/BoB are the most inclusive for non-individual entities.
- 📍 Remote/tribal area farmers: Local RRB or State Cooperative Bank — faster on-ground processing, NABARD refinancing available.
How to Choose the Right Bank for Your State in 2026
- 🗺️ Check your district’s lead bank: Under RBI’s Lead Bank Scheme, each district has one designated lead bank responsible for coordinating priority sector credit — this bank often has the most dairy loan experience and fastest appraisal.
- 🥛 Check your milk union’s bank tie-up: If you supply to a dairy cooperative or union (Amul, Sudha, Milkfed, Vijaya), ask which bank they route their member-farmer loans through — this bank already knows your milk production records, cutting weeks off verification.
- 🏘️ For 2–10 animal units: BoB Mini Dairy and Union Bank Finance to Dairy Sector are the two most specifically designed schemes — compare their nearest branch loan turnaround times.
- 🏭 For commercial-scale units and AHIDF: SBI or BoB with AHIDF route — both have active AHIDF processing experience at their zonal agriculture offices.
- 📍 For remote/rural areas: Your local Grameena Vikas Bank or State Cooperative Bank is often faster than driving 60 km to a commercial bank branch — and NABARD refinancing makes their rates competitive.
- 📞 Call before visiting: Call 2–3 branch agriculture officers directly and ask: current dairy rate, processing fee, turnaround time for Rs.X lakh unit. A 15-minute call saves weeks of wasted visits.
Documents Required for Dairy Farm Loan 2026
- 🪪 Identity proof: Aadhaar card, PAN card, Voter ID, or Driving License (any one)
- 🏠 Address proof: Aadhaar, utility bill, or ration card
- 📜 Land documents: Khasra/Khatauni/patta (ownership) or registered lease agreement for shed location
- 📋 Project report: Unit description, number and type of animals, shed dimensions, equipment list, projected milk output, milk marketing arrangement, and total project cost
- 🏦 Bank account details: Passbook/statement for loan disbursal and NABARD subsidy credit
- 📄 Caste certificate: If applying for SC/ST/women higher subsidy under DEDS (33.33%)
- 🥛 Milk society membership certificate: For SBI society-linked scheme or cooperative bank route
- 📸 Photographs: Passport-size photos plus site/shed photographs for physical verification
Pros and Cons of Public Bank Dairy Loans vs Private/NBFC Dairy Loans
| Factor | Public Sector Bank Dairy Loan | NBFC / Private Lender Dairy Loan |
|---|---|---|
| Interest Rate | 7.50%–8.75% p.a. — lower | 10%–16% p.a. — higher |
| DEDS/AHIDF Subsidy | ✅ Eligible — all 6 banks above | ❌ Most NBFCs not eligible |
| Collateral Requirement | Nil below Rs.1.6L–Rs.2L | Often requires collateral from Rs.50,000 |
| Processing Speed | 2–12 weeks (subsidy-linked = longer) | 3–10 working days (digital lending) |
| Documentation | Comprehensive; formal project report needed | Minimal; income proof sufficient |
| Loan Amount | Rs.50,000 to Rs.100 crore (AHIDF) | Typically Rs.50,000 to Rs.50 lakh |
| Moratorium Period | 3–6 months (standard); 24 months (AHIDF) | Usually nil or 1–2 months |
| Best For | Planned units; subsidy-eligible; 1–3 month timeline okay | Urgent capital need; established income; no time for formal appraisal |
Verdict: For any dairy unit where you have 4–8 weeks for the process, a public sector bank loan combined with DEDS subsidy is significantly cheaper than NBFC financing — saving Rs.40,000–Rs.1.5 lakh in interest over a 5-year term depending on loan size.
Important Dairy Loan Terms You Must Know – High-CPC Glossary
- 📌 MCLR (Marginal Cost of Funds Based Lending Rate): The internal benchmark below which banks cannot lend. All agricultural loan rates are MCLR + spread. SBI’s 1-yr MCLR = 8.80% (Oct 2026); Union Bank = 8.80% (Jul 2026).
- 📌 EBLR (External Benchmark Lending Rate): Repo-rate-linked benchmark. RBI repo rate = 8.00% (effective June 13, 2026). AHIDF MSME loans = EBLR + 200 bps = 10.00% before 3% subvention.
- 📌 Back-ended subsidy: The DEDS/AHIDF subsidy is not paid upfront — it is released to your loan account by NABARD after you make regular repayments for 3–6 months, reducing your outstanding principal.
- 📌 Hypothecation: The animals and equipment purchased with the loan are pledged to the bank as security without physical transfer. You retain possession and use — the bank has a legal charge over the assets.
- 📌 Moratorium period: A grace window (typically 3–6 months, up to 24 months for AHIDF) at loan start where you pay only interest, not full EMI — giving your dairy unit time to start producing and earning milk revenue before full repayment begins.
- 📌 Priority sector lending (PSL): RBI mandates all scheduled banks to lend at least 40% of their credit to priority sectors, including agriculture and allied activities like dairy. This obligation is why banks actively lend to dairy farmers even at lower rates — they need to meet their PSL targets.
- 📌 Lead bank: RBI-designated bank for priority sector credit coordination in each district. Your district’s lead bank will have the most dairy loan experience and fastest appraisal team. Check your district lead bank at rbi.org.in.
- 📌 CGTMSE guarantee: Credit Guarantee Fund Trust for Micro and Small Enterprises — covers dairy MSME loans up to Rs.5 crore (AHIDF) or up to Rs.2 crore (NABSanrakshan) without the borrower needing to provide land collateral. Critical for dairy entrepreneurs who lack land assets.
- 📌 KCC (Kisan Credit Card): A revolving credit facility for agricultural working capital. For dairy, covers recurring feed, veterinary, and labour costs at 7% p.a. GoI interest subvention up to Rs.3 lakh — effectively 4% with prompt repayment incentive.
- 📌 Processing fee waiver: BoB waives the fee up to Rs.3 lakh; Central Bank charges only 0.30% above Rs.3 lakh. For a Rs.5 lakh loan this means Rs.600 saving at Central Bank vs Rs.2,000 at BoB — minor but worth noting.
Important Links – Dairy Farm Loan 2026
| Resource | Link |
|---|---|
| Bank of Baroda Mini Dairy Unit Scheme (Official) | bankofbaroda.bank.in |
| Union Bank Finance to Dairy Sector (Official) | unionbankofindia.bank.in |
| Canara Bank Dairy Loans (Official) | canarabank.bank.in |
| SBI Allied Activities – Dairy (Official) | sbi.bank.in |
| NABARD DEDS Subsidy Guidelines | nabard.org |
| AHIDF Scheme – DAHD (Official) | dahd.gov.in |
| NDDB DIDF / AHIDF Schemes | nddb.coop |
| SBI Dairy Farm Loan – EMI Guide (Agrijob.in) | agrijob.in/sbi-dairy-farm-loan |
| NABARD Dairy Farm Loan 2026 Guide (Agrijob.in) | agrijob.in/nabard-dairy-farm-loan |
| Dairy Farm Loan Without Collateral 2026 (Agrijob.in) | agrijob.in/dairy-loan-no-collateral |
| DEDS Scheme 2026 – 25% Subsidy Guide (Agrijob.in) | agrijob.in/deds-scheme |
Conclusion – Best Bank for Dairy Farm Loan 2026
The best bank for dairy farm loan in 2026 is the one with a strong agri branch in your district and an active dairy-lending history — not necessarily the one with the lowest published headline rate. For a 2–10 animal mini unit, Bank of Baroda (8.70%, zero fee up to Rs.3 lakh) and Union Bank (84-month repayment) are the most practically structured. For the lowest cost, SBI at 7.50% p.a. allied-activities rate is the benchmark — especially when combined with NABARD’s DEDS 25% back-ended subsidy or AHIDF’s 3% GoI interest subvention. Before applying anywhere, call your nearest agri branch of 2–3 banks and ask for their current dairy loan rate, processing fee, and turnaround time — that 30-minute exercise is worth more than this or any comparison article. Bookmark this page — we update it every time RBI changes the repo rate or MCLR, and when NABARD revises subsidy guidelines.
- SBI offers the lowest dairy loan rate at 7.50% p.a. (allied activities, effective October 15, 2026).
- Bank of Baroda’s Mini Dairy Scheme at 8.70% p.a. is the clearest-structured product for 2–10 animal units — zero processing fee up to Rs.3 lakh.
- Union Bank offers the longest repayment: 84 months (7 years) — best for new farmers needing time to build milk revenue.
- NABARD DEDS subsidy of 25% (33.33% for SC/ST) is combinable with any bank — on a Rs.5 lakh unit this returns Rs.1.25–Rs.1.67 lakh to your loan account.
- AHIDF’s 3% Government interest subvention (approved 439+ projects worth Rs.21,190 crore as of July 2026) applies to dairy processing infrastructure — not just animal purchase.
- Your best dairy bank is the one your local milk union already works with — not necessarily the one with the published lowest rate.
Frequently Asked Questions About Best Bank for Dairy Farm Loan 2026
Which bank is best for a dairy farm loan in 2026?
For 2–10 animal mini units, Bank of Baroda (8.70% p.a., zero processing fee up to Rs.3 lakh) is the most clearly structured. For the lowest rate overall, SBI (from 7.50% p.a.) leads. For the longest repayment tenure, Union Bank (84 months) is best. For company/NGO applicants, Central Bank’s Cent Dairy Scheme (8.75%) accepts the broadest entity types. The universal rule: choose the bank with the strongest agri-lending track record in your specific district.
What is the SBI dairy farm loan interest rate in 2026?
SBI’s allied activities dairy loan rate is 7.50% p.a. onwards, effective October 15, 2026. This is benchmarked to SBI’s 1-year MCLR (8.80% as of October 2026) with a priority-sector concession applied for dairy. KCC working capital for dairy animals is available at 7% p.a. up to Rs.3 lakh with GoI interest subvention, reducing to 4% effective rate with the 3% Prompt Repayment Incentive.
What is Bank of Baroda’s dairy loan scheme and what is its interest rate?
Bank of Baroda’s main dairy product is the Scheme for Financing Mini Dairy Units at 8.70% p.a. (MCLR-linked) for 2–10 milch animals. The processing fee is zero up to Rs.3 lakh and 1% above. The maximum loan is Rs.6 lakh (10 animals) with a 5-year repayment period and 3-month moratorium. Bank of Baroda also offers a separate KCC for Animal Husbandry and Fisheries for working capital needs up to Rs.10 lakh.
What is AHIDF and what interest subvention does it offer in 2026?
AHIDF (Animal Husbandry Infrastructure Development Fund) is a Government of India scheme administered by DAHD providing a 3% per annum interest subvention on bank loans for dairy processing, value-added dairy products, and cooperative dairy infrastructure. As of July 2026, AHIDF has approved 439+ projects worth Rs.21,190.68 crore benefitting approximately 25 lakh farmers. The subvention is available for up to 8 years including a 2-year moratorium. Eligible entities include MSMEs, FPOs, private companies, cooperatives, and individual entrepreneurs.
What is the NABARD DEDS subsidy for dairy farm loans in 2026?
Under DEDS (Dairy Entrepreneurship Development Scheme), NABARD provides a 25% back-ended capital subsidy for general category applicants and 33.33% for SC/ST farmers. For a standard 10-animal dairy unit costing Rs.5 lakh, this means Rs.1.25 lakh back (general) or Rs.1.67 lakh (SC/ST) credited to your loan account after 3–6 months of regular repayments. The subsidy is available via all major scheduled commercial banks.
Can I get a dairy farm loan without land collateral?
Yes. Bank of Baroda offers no-collateral dairy loans up to Rs.1.6 lakh (hypothecation of animals only). Union Bank is collateral-free up to Rs.2 lakh. Canara Bank requires nil collateral up to Rs.2 lakh. Beyond these limits, PMEGP and Mudra (Tarun) loans up to Rs.10 lakh are available without land collateral via any scheduled bank. CGTMSE guarantee covers AHIDF dairy MSME loans up to Rs.5 crore without requiring land assets.
What documents do I need for a dairy farm loan application?
Standard documents include: identity proof (Aadhaar/PAN), address proof (Aadhaar/utility bill), land ownership or lease papers for the shed location, a detailed project report (animal count, shed cost, equipment, milk output projection, and marketing arrangement), bank passbook for disbursal, and caste certificate if claiming SC/ST or women-category DEDS subsidy. Milk cooperative membership certificate is needed for SBI’s society-linked scheme.
Do RRBs and cooperative banks give dairy loans in 2026?
Yes. Regional Rural Banks (RRBs) and State Cooperative Banks are eligible NABARD refinancing institutions for all dairy schemes including DEDS. For farmers in remote districts, RRBs like Baroda UP Bank, Madhyanchal Gramin Bank, and state cooperative banks often process dairy loans faster than commercial bank branches due to proximity and familiarity with local milk union and land records.
How long does dairy farm loan approval take?
A pure bank dairy loan without subsidy linkage can be approved in 2–4 weeks at an efficient agri branch with all documents in order. NABARD DEDS-linked loans add 4–8 weeks for subsidy registration and verification. AHIDF-routed loans involve DAHD portal registration and may take 8–12 weeks for first disbursal. Having a pre-prepared, detailed project report with all documents ready is the single biggest factor in cutting approval time.
What is the Cent Dairy Scheme of Central Bank of India?
Central Bank of India’s Cent Dairy Scheme is a dedicated dairy unit financing product at 8.75% p.a. with 0% processing fee up to Rs.3 lakh and 0.30% above Rs.3 lakh. It is open to farmers, individuals, groups of farmers, companies, societies, firms, and NGOs — making it the most inclusive entity-wise among the six banks compared. Loan amount is determined by project profitability and repayment capacity.
Interest rates and scheme details verified against: SBI Allied Activities page (w.e.f. 15.10.2026) · BoB Mini Dairy Scheme · Union Bank Dairy · Canara Bank Dairy Loans · NDDB AHIDF/DIDF · DAHD (Department of AH & Dairying)
Disclaimer: Interest rates, processing fees, and subsidy norms change periodically with RBI MCLR revisions and government budget circulars. Always confirm the current applicable rate and terms directly with your specific bank branch or agri loan officer before applying. This guide is for informational purposes only and does not constitute financial or legal advice.
This guide is reviewed and updated regularly for accuracy. Bookmark this page — we update it every time RBI revises MCLR/repo rates or NABARD/DAHD issues new dairy scheme circulars.
Last Updated: October 2026 | Author: NITISH SINGH (Ex-Central Bank of India Loan Officer, M.Sc. Agriculture)