
Sustainable agriculture loan 2026 programs are reshaping how Indian farmers finance their shift to eco-friendly practices — with select banks now offering effective interest rates as low as 4% per annum for green farm activities. If you are a farmer, FPO member, or agri-entrepreneur looking to adopt organic cultivation, precision farming, or water-efficient irrigation, this guide covers every scheme, rate, and eligibility rule you need in one place.
This guide is for Indian farmers (individual and group), Farmer Producer Organisations (FPOs), Self Help Groups (SHGs), agri-startups, and rural entrepreneurs aged 20–60 who want to reduce borrowing costs while transitioning to sustainable or organic farming practices. It covers 7 active bank programs, government schemes with 3% interest subvention, eligibility criteria, step-by-step application process, and a comparison of all major green agriculture loan options available in India as of October 2026.
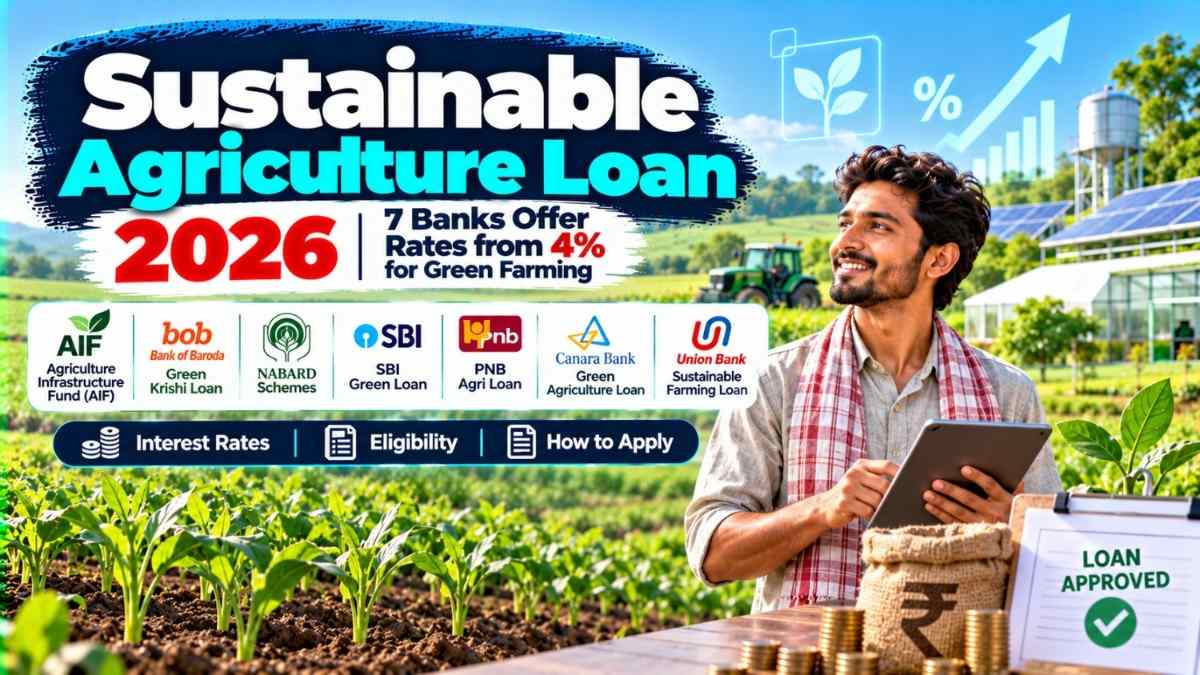
Sustainable agriculture loans in India in 2026 are available at effective rates as low as 4% per annum. The Agriculture Infrastructure Fund (AIF) offers 3% interest subvention on loans up to Rs.2 crore for 7 years. Bank of Baroda’s bob Green Krishi scheme provides a 0.50% concession specifically for certified organic farmers, while NABARD’s Rs.1,300 crore green funds further lower refinancing costs for state-level climate farming projects.
- Lowest Effective Rate: 4% per annum (KCC crop loans with full interest subvention)
- AIF Subvention: 3% per annum on loans up to Rs.2 crore for up to 7 years
- SBI Agriculture Loan Rate: From 7.50% p.a. (as of 15.10.2026)
- Bank of Baroda bob Green Krishi: 0.50% concession for certified organic farmers
- NABARD Green Impact Fund: Rs.1,000 crore fund to lower costs for climate farming
- NABARD Carbon Fund: Rs.300 crore for carbon-focused agri start-ups (2026)
- AIF Eligible Entities: Individual farmers, FPOs, SHGs, JLGs, PACS, agri-startups
- Maximum AIF Loan Projects: Up to 25 projects at different locations per entity
- Credit Guarantee: CGTMSE covers loans up to Rs.2 crore — no collateral needed
- Canara Bank Agriculture Rate: MCLR + 1.40% spread for loans up to Rs.3 lakh (updated 18.08.2026)
📋 Table of Contents
- What Is a Sustainable Agriculture Loan and How It Works in 2026
- Who Should Apply for a Green Farming Loan
- Interest Rates: 7 Banks Offering Lower Rates for Green Farm Practices
- Eligibility and Document Requirements
- How to Apply: Step-by-Step Process
- AIF Scheme vs KCC Loan: Which Is Better for Sustainable Farmers
- Pros and Cons of Sustainable Agriculture Loans
- Important Terms Related to Green Agriculture Finance
- Important Dates and Deadlines 2026
- Important Links
- Conclusion
- Key Takeaways
- Frequently Asked Questions
What Is a Sustainable Agriculture Loan and How It Works in 2026
A sustainable agriculture loan is a subsidised or concessional credit product extended by banks and financial institutions specifically for farming activities that improve soil health, reduce chemical inputs, conserve water, or lower carbon emissions. Unlike a standard crop loan, these green loan products carry lower interest rates, longer repayment tenures, and in many cases, full credit guarantee coverage — making them ideal for farmers transitioning away from conventional chemical-intensive agriculture.
In 2026, India’s sustainable agriculture finance ecosystem is anchored by three pillars: the government’s Agriculture Infrastructure Fund (AIF) offering 3% annual interest subvention, NABARD’s newly launched Rs.1,300 crore green fund complex, and individual bank schemes like Bank of Baroda’s bob Green Krishi that reward certified organic farmers with rate concessions of 0.50% or more. The result is that an Indian farmer practicing organic cultivation or adopting precision irrigation can now borrow at an effective rate of 4%–7% — compared to 11%–14% from informal lenders.
The core mechanism is interest subvention: the Government of India or the bank absorbs part of the interest cost upfront, and the borrower pays only the reduced net rate. NABARD refinances participating banks at lower rates, which banks pass on to farmers. This chain — government subvention → NABARD refinance → bank lending → farmer benefit — is how India’s green credit architecture lowers costs without compromising bank viability.
| Green Loan Type | Nominal Rate | Effective Rate After Subvention | Tenure |
|---|---|---|---|
| KCC Crop Loan (up to Rs.3 lakh) | 7% | 4% (3% Centre + state top-up) | Up to 12 months (revolving) |
| AIF Post-Harvest Infrastructure | ~9% | ~6% (after 3% GoI subvention) | Up to 7 years |
| bob Green Krishi (Organic) | As per scale of finance | 0.50% lower than standard rate | Short term (crop cycle) |
| SBI Agriculture Loan | 7.50% onwards | 4%–7% with subvention | 1–15 years |
| NABARD Refinance (Green) | 4.5% (to banks) | Banks lend lower than market | Project-based |
Who Should Apply for a Green Farming Loan
- 🧑🌾 Individual farmers transitioning to organic cultivation — those who have begun the 2–3 year conversion period and need finance for non-chemical inputs, bio-fertilisers, and certification costs
- 📦 FPO and cooperative members — Farmer Producer Organisations and PACS groups wanting to set up collective post-harvest infrastructure like cold storage, grading units, or pack houses with 3% AIF subvention
- 💧 Farmers adopting drip or sprinkler irrigation — water-efficient irrigation projects qualify for NABARD’s 50 basis points additional rebate under innovative agriculture activities
- 🌿 Horticulture and plantation crop farmers — fruits, vegetables, and spice growers eligible for green loans under both AIF and bank-specific organic schemes
- 🚀 Agri-startups and agri-entrepreneurs — early-stage ventures working on precision farming, vermicomposting, hydroponics, or mushroom cultivation, all explicitly listed under AIF eligible projects
- 🤝 Joint Liability Groups (JLGs) and Self Help Groups (SHGs) — collateral-free green loans with CGTMSE guarantee coverage up to Rs.2 crore make these groups strong candidates
- 🏛️ State government and PPP project sponsors — NABARD’s Green Impact Fund specifically targets state-level climate adaptation projects like crop diversification and water-efficient farming
- 📊 Farmers with existing KCC accounts — those who repay promptly can get the additional 3% interest rebate, bringing effective rates to 4% on short-term crop loans
Interest Rates: 7 Banks Offering Lower Rates for Green Farm Practices
Seven major Indian banks and financial institutions currently offer structured lower interest rates for sustainable or green agricultural practices in 2026. Here is a verified rate comparison drawn from official bank websites and NABARD data.
| # | Bank / Institution | Green Scheme Name | Interest Rate 2026 | Key Green Benefit |
|---|---|---|---|---|
| 1 | Government of India (via all SCBs) | Agriculture Infrastructure Fund (AIF) | Market rate minus 3% subvention (effective ~6%–7%) | 3% p.a. subvention for 7 years on loans up to Rs.2 crore |
| 2 | State Bank of India | KCC + Interest Subvention | 7% nominal; effective 4% with full subvention | Lowest effective rate for promptly repaying farmers |
| 3 | Bank of Baroda | bob Green Krishi | Standard rate minus 0.50% for loans above Rs.3 lakh | Only scheme in India with dedicated organic farming concession |
| 4 | Punjab National Bank | Organic Farming Scheme + Greenhouse Loans | 7.7%–9.9% (NABARD refinance eligible) | Organic inputs, greenhouse financing, FPO credit |
| 5 | Canara Bank | Agriculture Loans (Revised 18.08.2026) | MCLR + 1.40% spread (loans up to Rs.3 lakh) | Lowest spread tier for small and marginal farmers |
| 6 | HDFC Bank | AIF Scheme (Partner Bank) | ~7%–9% with 3% AIF subvention applied | No minimum loan cap; CGTMSE guarantee — no collateral needed |
| 7 | NABARD (via RRBs and Co-op Banks) | Green Impact Fund + Short-Term Refinance | 4.5% refinance rate to banks (crop loans) | Rs.1,000 crore NGIF lowers costs for state climate projects |
Bank of Baroda’s bob Green Krishi is India’s only bank scheme that provides an additional Rs.10,000 per acre above the standard scale of finance to cover organic certification costs — a unique benefit that no competitor bank currently matches. If you are already enrolled in organic certification under India’s National Programme for Organic Production (NPOP), apply through bob Green Krishi before any other scheme.
Eligibility and Document Requirements for Sustainable Agriculture Loans
Eligibility for green or sustainable agriculture loans in 2026 varies by scheme. The AIF scheme has the broadest eligibility among all government programs. Here is a consolidated eligibility guide.
Who is eligible under AIF (Agriculture Infrastructure Fund):
- Individual farmers and groups of farmers
- Farmer Producer Organisations (FPOs) and Farmer Producer Companies (FPCs)
- Self Help Groups (SHGs)
- Joint Liability Groups (JLGs)
- Primary Agriculture Credit Societies (PACS)
- Marketing Cooperative Societies and Multipurpose Cooperative Societies
- Agri-entrepreneurs and agri-startups
- State agencies and PPP project sponsors (Central and State government backed)
Who is eligible under bob Green Krishi (Bank of Baroda):
- Individual farmers and groups of farmers
- Corporate farmers, FPOs, cooperatives, proprietorship and partnership firms
- Farmers already practicing organic cultivation and enrolled for organic certification
- Traditional farmers transitioning to organic — must have begun NPOP certification process
| Document Required | AIF Scheme | KCC / General Green Loan | bob Green Krishi |
|---|---|---|---|
| Land ownership / lease document | Required | Required | Required |
| Aadhaar card | Required | Required | Required |
| Organic certification enrollment proof | Not required | Not required | Mandatory |
| Project / business plan | Required (post-harvest infrastructure) | Not required | Optional (for higher amounts) |
| Bank account (6-month statement) | Required | Required | Required |
| CGTMSE registration | Auto-covered by bank | Not applicable | Not applicable |
| Photograph (passport size) | Required | Required | Required |
Additional eligibility for full interest subvention on KCC loans: Farmers must repay the short-term crop loan within the due date to avail the additional 3% interest subvention, bringing the effective rate from 7% to 4%. Delayed repayment forfeits the subvention benefit for that cycle.
How to Apply for a Sustainable Agriculture Loan — Step-by-Step Process
- Identify the right scheme: Decide whether you need a short-term crop loan (KCC), a post-harvest infrastructure loan (AIF), or an organic farming working capital loan (bob Green Krishi). The purpose of the loan determines which scheme is applicable.
- Check eligibility: Visit the AIF Online Portal at agriinfra.dac.gov.in or your nearest bank branch. AIF has an online eligibility checker on myscheme.gov.in. For bob Green Krishi, contact the nearest Bank of Baroda rural branch.
- Prepare documents: Gather land records, Aadhaar, organic certification enrollment proof (if applicable), project business plan (for AIF), and 6-month bank statements. AIF document checklist is available at agriinfra.dac.gov.in/Home/CheckList.
- Submit application online or offline: AIF applications are submitted online through the official AIF portal (agriinfra.dac.gov.in). KCC and bob Green Krishi applications can be submitted at the nearest branch. Offline applications must also be entered on the AIF portal by the lending institution.
- Bank processing and approval: The bank has a maximum of 60 days from application date to communicate its decision under the AIF scheme. For KCC renewals, the processing is usually faster — 7–15 working days.
- Loan sanction and disbursement: On approval, the bank sanctions the loan and applies the interest subvention benefit upfront. For AIF, 75% of the project cost can be financed, with the remaining 25% as borrower contribution (which may be reduced by convergent capital subsidies).
- Repayment aligned to cash flows: AIF loans carry monthly, quarterly, or half-yearly instalments depending on the project’s cash flow. KCC repayment is aligned to the crop harvest and marketing cycle. Timely repayment qualifies the farmer for continued subvention in the next cycle.
AIF Scheme vs KCC Loan — Which Is Better for Sustainable Farmers in 2026
The AIF scheme and the Kisan Credit Card (KCC) are the two most widely used instruments for sustainable agriculture finance in India. They serve different purposes and complement each other — but many farmers choose the wrong one for their need, losing out on maximum benefit.
| Parameter | AIF Scheme (Agriculture Infrastructure Fund) | KCC Loan (Kisan Credit Card) |
|---|---|---|
| Purpose | Post-harvest infrastructure, cold storage, organic inputs units, precision farming assets | Crop production inputs — seeds, fertilisers, labour, irrigation |
| Loan Amount | No ceiling; subvention up to Rs.2 crore per project; up to 25 projects | No ceiling; subvention on prompt repayment up to Rs.3 lakh |
| Interest Subvention | 3% p.a. for up to 7 years (GoI bears the cost) | 3% prompt-repayment subvention + state top-up (total up to 4%) |
| Effective Interest Rate | ~6%–7% (market rate minus 3%) | 4% with full subvention on timely repayment |
| Collateral Requirement | None up to Rs.2 crore (CGTMSE covers — fee paid by GoI) | None for small loans; hypothecation of crops |
| Tenure | Up to 7 years including moratorium | Revolving — 12 months, renewed annually for 5 years |
| Repayment Schedule | Monthly/Quarterly/Half-yearly per project cash flow | After harvest and crop sale |
| Who benefits most | FPOs, agri-startups, infrastructure investors, post-harvest value chain players | Individual farmers with regular crop cultivation needs |
| Green farming applicability | Best for organic input production units, precision farming, drip systems | Best for buying organic seeds, bio-fertilisers, natural pesticides |
| Convergence with other schemes | Yes — combinable with MIDH, PM KUSUM, NHB, PMEGP subsidies | Limited convergence |
For individual farmers growing organic crops and needing seasonal working capital, the KCC with interest subvention is the better choice — its 4% effective rate is unmatched. For FPOs, agri-startups, or any farmer wanting to build post-harvest infrastructure like cold storage or grading units that generate ongoing income, the AIF scheme is superior — the 3% subvention over 7 years, combined with zero-collateral CGTMSE coverage and convergence with PM KUSUM and MIDH subsidies, makes it India’s most powerful green agriculture finance tool in 2026.
Pros and Cons of Sustainable Agriculture Loans
Advantages of Green Agriculture Loan Programs:
- Dramatically lower interest costs: Effective rates of 4%–7% versus 11%–18% from informal moneylenders — a saving of Rs.40,000–Rs.90,000 annually on a Rs.10 lakh loan
- No collateral for loans up to Rs.2 crore: CGTMSE coverage under AIF eliminates the need for property mortgage, making green credit accessible to small and marginal farmers
- Long repayment tenure: AIF offers up to 7 years including moratorium — giving infrastructure investors time to generate cash flows before full repayment kicks in
- Combinable with other subsidies: AIF benefits can be stacked with PM KUSUM, MIDH, NHB, PMEGP, and other capital subsidies — reducing net project cost significantly
- Rewards timely repayment: KCC prompt-repayment subvention incentivises financial discipline, building farmers’ formal credit history
Limitations and Disadvantages to Consider:
- Organic certification is mandatory for some schemes: bob Green Krishi requires NPOP enrollment, which takes 2–3 years — so recently converted farmers cannot immediately access the organic concession
- AIF subvention is project-based, not income-based: Individual farmers without an infrastructure project plan cannot access the AIF scheme — it is not a general-purpose crop loan
- 60-day processing timeline under AIF: Banks have up to 60 days to decide on AIF applications — slower than KCC renewals (7–15 working days)
Important Terms Related to Green Agriculture Finance
- Interest Subvention: A government-funded partial absorption of loan interest. The borrower pays a lower rate; the government compensates the bank for the difference. Currently 3% under AIF and KCC schemes.
- NABARD Green Impact Fund (NGIF): A Rs.1,000 crore fund launched in January 2026, financed from NABARD’s profits, designed to lower borrowing costs for state-level climate adaptation projects including crop diversification and water-efficient farming.
- NABARD Carbon Fund (NCF): A Rs.300 crore fund targeting carbon developers and agri-startups working on emissions reduction and carbon capture — largely underserved by conventional finance.
- CGTMSE (Credit Guarantee Fund Trust for Micro and Small Enterprises): A government-backed guarantee mechanism that allows banks to lend up to Rs.2 crore without collateral. Under AIF, the guarantee fee is paid by the Government of India for up to 7 years.
- KCC (Kisan Credit Card): A revolving credit facility for crop production needs. Short-term loans up to Rs.3 lakh at 7% nominal rate, reducible to 4% effective with prompt repayment subvention.
- MCLR (Marginal Cost of Funds-Based Lending Rate): The benchmark rate banks use to price loans. Agricultural loans are priced as MCLR + a spread (e.g. MCLR + 1.40% for Canara Bank agriculture loans up to Rs.3 lakh).
- Scale of Finance (SOF): The district-level crop-specific ceiling set by the State Level Bankers’ Committee (SLBC) for short-term crop loans. bob Green Krishi adds Rs.10,000 per acre above this SOF for certified organic farmers.
- NPOP (National Programme for Organic Production): India’s official organic certification framework governed by APEDA under the Ministry of Commerce. Enrollment in NPOP is a prerequisite for bob Green Krishi eligibility.
- Precision Agriculture Loan: Finance for technology-driven farming — IoT sensors, drone-based crop monitoring, GPS-guided machinery. Eligible under AIF’s “infrastructure for smart and precision agriculture” category.
- Vermicomposting Finance: Loans for organic compost production from earthworms, explicitly listed as an eligible community farming asset under AIF — attractive for farmers producing organic inputs for sale.
Important Dates and Timeline for Green Agriculture Loans 2026
| Event / Milestone | Date / Timeline |
|---|---|
| NABARD Green Impact Fund (NGIF) and Carbon Fund launched | January 2026 |
| SBI Agriculture Segment Interest Rate updated | 15 October 2026 |
| Canara Bank Agriculture Interest Rate updated | 18 August 2026 |
| West Bengal AIF Scheme page last updated | 26 June 2026 |
| Bihar additional 1% NABARD interest subsidy (2025–26 FY) | January 2026 onwards |
| KCC crop loan Rabi cycle application window | October–November 2026 (check with your bank) |
| AIF Loan Decision Deadline (bank to farmer) | Maximum 60 days from application |
| AIF Interest Subvention Period Maximum | 7 years including moratorium |
| KCC Prompt Repayment Deadline (for subvention) | As per crop cycle due date — confirm with issuing bank |
Important Links
| Resource | Link |
|---|---|
| AIF Official Portal (Apply Online) | agriinfra.dac.gov.in |
| AIF Eligibility Checker (myscheme.gov.in) | myscheme.gov.in/schemes/aif |
| NABARD Official Website | nabard.org |
| SBI Agriculture Loan Interest Rates (Official) | SBI Agriculture Rate Page |
| Bank of Baroda bob Green Krishi (Official) | bankofbaroda.bank.in |
| PNB Organic Farming Loan Scheme | pnb.bank.in |
| Agrijob.in — NABARD Dairy Farm Loan Guide | NABARD Dairy Farm Loan 2026 |
| Agrijob.in — Agri-NBFCs India 2026 | Agri-NBFCs India 2026 Comparison |
Conclusion
Sustainable agriculture loans in 2026 give Indian farmers a genuine financial incentive to go green — not just an environmental obligation. With effective rates as low as 4% under the KCC-subvention model, a 3% annual subvention on AIF infrastructure loans for up to 7 years, Bank of Baroda’s first-of-its-kind organic farming concession through bob Green Krishi, and NABARD’s Rs.1,300 crore green fund complex actively lowering refinancing costs, the economic case for sustainable farming has never been stronger. Your next step is to identify whether your farming activity qualifies for the AIF scheme, the KCC subvention, or a bank-specific green product — then visit the official AIF portal at agriinfra.dac.gov.in or your nearest bank branch to begin your application. Bookmark this page — we update it every time NABARD or the government revises rates or eligibility rules.
- Sustainable agriculture loans in India offer effective rates from 4% p.a. — the AIF scheme gives 3% annual subvention on loans up to Rs.2 crore for 7 years
- Bank of Baroda’s bob Green Krishi is India’s only dedicated organic farming loan with a 0.50% rate concession and Rs.10,000/acre organic certification support above the standard scale of finance
- NABARD launched a Rs.1,000 crore Green Impact Fund and Rs.300 crore Carbon Fund in January 2026 to lower climate farming costs for states and agri-startups
- AIF loans up to Rs.2 crore require zero collateral — CGTMSE guarantee fee is paid by the Government of India, not the borrower
- KCC short-term crop loans offer the lowest rate (4% effective) for farmers who repay promptly — apply before the Rabi cycle window closes in November 2026
Frequently Asked Questions About Sustainable Agriculture Loan 2026
What is the lowest interest rate available on a sustainable agriculture loan in India in 2026?
The lowest effective interest rate on a sustainable agriculture loan in India in 2026 is 4% per annum, available on Kisan Credit Card (KCC) crop loans up to Rs.3 lakh. This rate is achieved through a 3% interest subvention from the Central Government plus an additional 1% from some states like Bihar, provided the farmer repays the loan on time within the crop cycle due date.
What is the Agriculture Infrastructure Fund (AIF) and how does its 3% subvention work?
The Agriculture Infrastructure Fund (AIF) is a Central Sector Scheme offering medium- to long-term debt financing for post-harvest management infrastructure and community farming assets. All loans up to Rs.2 crore sanctioned under AIF carry a 3% annual interest subvention paid by the Government of India directly to the lending bank. This reduces the borrower’s effective rate by 3 percentage points for up to 7 years, including any moratorium period. Eligible entities include individual farmers, FPOs, SHGs, agri-startups, and cooperative societies.
What is Bank of Baroda’s bob Green Krishi and who can apply?
bob Green Krishi is Bank of Baroda’s dedicated sustainable agriculture loan scheme aligned with India’s National Programme for Organic Production (NPOP) and ESG goals. It provides a 0.50% interest concession for loans above Rs.3 lakh and an additional Rs.10,000 per acre above the standard scale of finance to cover organic certification and increased input costs. Eligible applicants include individual farmers, corporate farmers, FPOs, cooperatives, and proprietorship or partnership firms already practicing or enrolled for organic cultivation. Funds must be used exclusively for organic-compliant inputs and farming activities.
Does AIF require collateral for loans up to Rs.2 crore?
No. Under the Agriculture Infrastructure Fund (AIF), loans up to Rs.2 crore are covered by the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE). The government pays the CGTMSE guarantee fee on behalf of the borrower for a maximum period of 7 years. This means eligible farmers, FPOs, SHGs, and agri-startups can access up to Rs.2 crore without mortgaging any land or property.
What did NABARD launch in 2026 for green and sustainable farming?
NABARD launched two new thematic funds in January 2026: the Rs.1,000 crore NABARD Green Impact Fund (NGIF) and the Rs.300 crore NABARD Carbon Fund (NCF). The NGIF is financed from NABARD’s own profits and uses interest income to lower borrowing costs for state governments implementing climate adaptation projects, including crop diversification and water-efficient farming. The NCF targets carbon developers and agri-startups working on emissions reduction and carbon capture. Together, these funds represent India’s largest institutional commitment to green agriculture finance in a single year.
Can AIF benefits be combined with other government schemes like PM KUSUM or MIDH?
Yes. One of the most powerful features of the Agriculture Infrastructure Fund is that its benefits can be combined with other government subsidies. The AIF scheme is in active convergence with PM KUSUM (solar pump subsidies), MIDH (horticulture development), NHB (National Horticulture Board), PMEGP (micro-enterprise grants), ACABC (Agri-clinics and Agri-business Centres), and AMI (Agriculture Marketing Infrastructure). Stacking these schemes can dramatically reduce the net project cost for a sustainable farming infrastructure investment.
What is the NABARD short-term refinance rate for crop loans in 2026?
NABARD’s short-term refinance rate for State Cooperative Banks and Commercial Banks or RRBs financing crop loans stands at 4.5% per annum as per NABARD’s published rates. This concessional refinance rate — well below standard market lending rates — enables participating banks to offer farmers lower effective interest rates on short-term crop loans, particularly under the Kisan Credit Card scheme.
How long does AIF loan approval take and what is the maximum number of projects allowed?
Under the Agriculture Infrastructure Fund, the lending institution has a maximum of 60 days from the date of loan application to communicate its decision to the applicant. An eligible entity can undertake up to 25 projects at different locations under the AIF scheme, with each project eligible for interest subvention on loans up to Rs.2 crore. This means a large FPO or cooperative could theoretically access AIF subvention across 25 separate post-harvest infrastructure projects simultaneously.
What types of green farming projects are eligible under AIF?
The AIF scheme covers a wide range of sustainable and green agriculture projects including: warehouses and cold storage, grading and sorting units, pack houses and ripening chambers, organic inputs production (including vermicomposting units), infrastructure for smart and precision agriculture (IoT and AI-based systems), hydroponic farming, mushroom cultivation, vertical and aeroponic farming, and tissue culture units. Any viable post-harvest management infrastructure or community farming asset that meets the scheme’s project feasibility criteria is eligible.
What happens if I miss the repayment deadline on a KCC crop loan with interest subvention?
If a farmer misses the repayment due date on a Kisan Credit Card (KCC) crop loan, the additional 3% prompt-repayment interest subvention is forfeited for that crop cycle. The farmer will be charged the full 7% nominal rate instead of the subsidised 4% effective rate. Repeated late repayments can also affect the farmer’s credit score and may jeopardise KCC renewal for the next crop cycle. Always prioritise repaying within the crop cycle due date to retain the subvention benefit.
📅 Last Updated: October 2026 | Data sourced from nabard.org, agriinfra.dac.gov.in, myscheme.gov.in, bankofbaroda.bank.in, sbi.bank.in, and pnb.bank.in. This guide is reviewed and updated regularly for accuracy. Bookmark this page for the latest sustainable agriculture loan 2026 information.
⚠️ Disclaimer: This article is for informational purposes only. Interest rates, scheme eligibility, and loan terms are subject to change by the respective banks and government authorities. Always verify current rates and eligibility at the official bank website or nearest branch before applying. This is not financial advice.